
Two of our real sponsors aren't anywhere near our shop. OG Racing, our safety-gear supplier, is in Virginia. We race out of Colorado Springs. FCP Euro, our parts partner, is states away too. Neither fact has ever once come up in a contract conversation, and that surprises almost every racer I tell it to.
Here's the thing about a sponsor check that clears from a different state than the one on your license: almost nothing changes. A couple of things genuinely do. Knowing which is which keeps you from panicking over a non-issue or missing the one thing that's real. It's exactly the kind of question The Funded Season Kit is built to answer once — instead of googling it fresh every time a new partner signs.
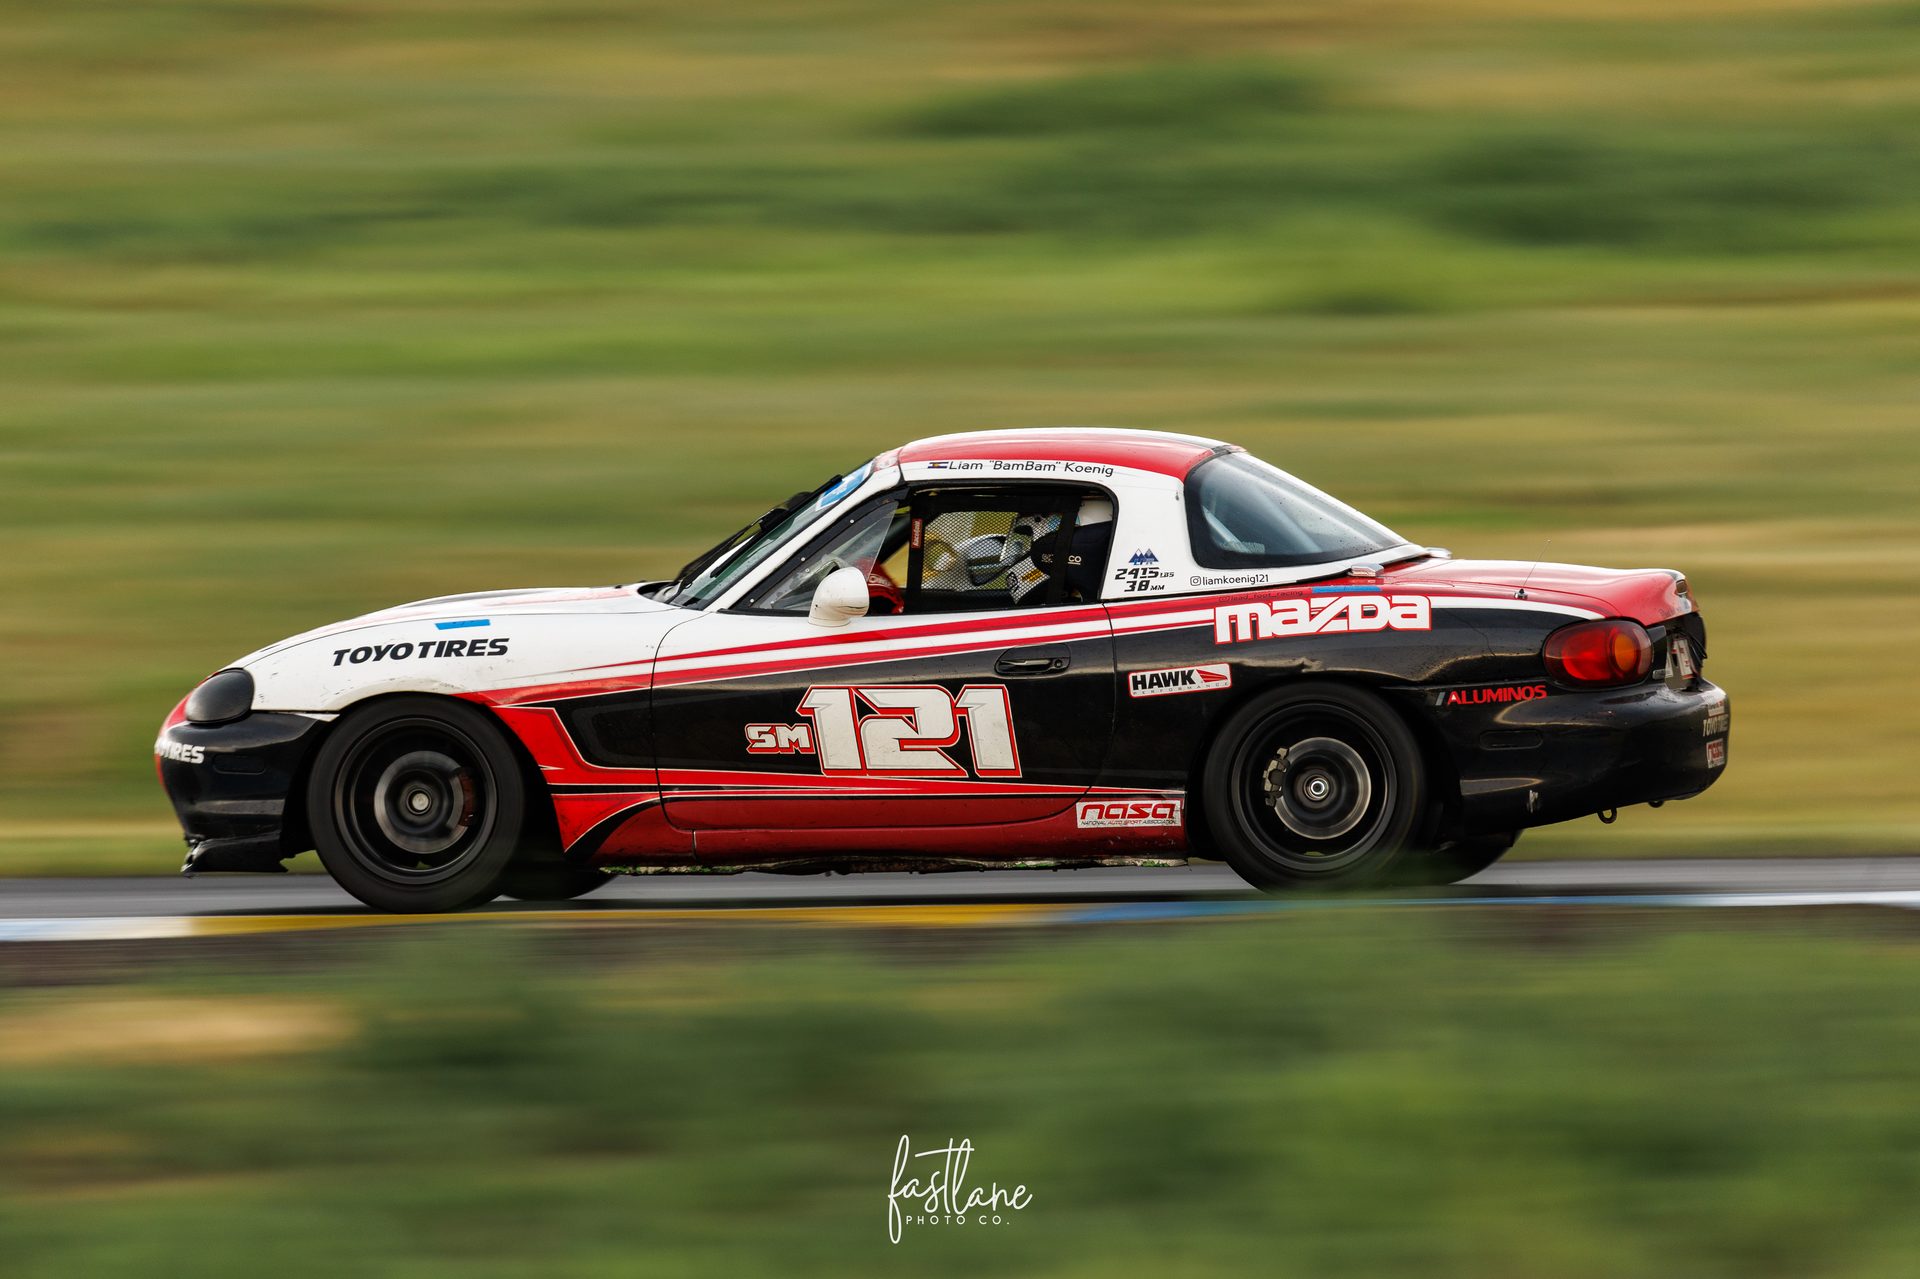 Our cars race in Colorado. Some of our sponsors have never set foot here — and that's completely normal.
The two things racers worry about that aren't real problems
"Do I owe sales tax in their state now?" No. Sales tax nexus — the legal trigger that makes you responsible for collecting or paying a state's sales tax — attaches to a seller making sales into a state, not to someone who receives a payment mailed from a company based there. The post-Wayfair economic-nexus rules that states use are built around a seller crossing a sales threshold into that state, not a sponsor's zip code on a check. A sponsorship payment for putting a decal on your door is an advertising arrangement, not a retail sale. I couldn't find a single state sales-tax code that treats it otherwise. If your situation is actually a product-sale relationship — you're reselling their gear, not just wearing their logo — that's a different conversation. Ask an accountant before assuming either way.
"Do I owe that state income tax?" This one has a real name — the "jock tax" — and it's a real legal concept. Professional athletes genuinely do owe nonresident income tax in states where they physically perform, allocated by a "duty days" formula: days worked in that state divided by total work days, times total pay. Roughly 41 states run some version of it. But it exists specifically because a traveling pro athlete performs services inside the taxing state — games, practices, appearances, all physically there. A club racer who gets sponsored by a company two states away and never drives a single lap in that state has none of the fact pattern the jock tax is built around. This is a pro-sports mechanism, not a grassroots-racing one, and treating it like a looming threat is worrying about the wrong thing.
The one thing that genuinely doesn't care where anyone lives
The federal 1099-NEC threshold doesn't check anyone's address. Starting with 2026 payments, a business has to issue you a 1099-NEC once it pays you $2,000 or more across the year for services — under the One Big Beautiful Bill Act, which raised the old $600 threshold. That rule triggers on the dollar amount, full stop. It applies the same whether your sponsor is down the street or across the country. We walked through the W-9/invoice side of this in how to invoice a racing sponsor — read that for the mechanics. The only thing geography changes here is nothing.
This is exactly why "paperwork" belongs in a system, not a shoebox of screenshots. The Funded Season Kit has a working sponsor tracker spreadsheet built in — one row per partner, one column for every number that has to match across a W-9, an invoice, and a 1099 at tax time. It doesn't matter if partner #1 is local and partner #3 is four states away. The same row format handles both.
The thing that actually changes: who pays to get you there
If a sponsor wants you to show up somewhere — a store opening, a trade-show booth, a meet-and-greet with their customers — and "somewhere" is their state, not yours, that's a real logistics line that has to get written down. Standard practice in endorsement and sponsorship contracts has the company cover the athlete's travel, lodging, and meal costs for a requested appearance. That's the custom, not a law — nobody's required to write it that way. But if your agreement is silent on it, you're the one eating a plane ticket for a deal you can't recoup on, and that's a conversation worth having before you say yes, not after you've bought the flight.
 The race happens wherever your schedule says. An appearance clause decides who pays to get you to theirs.
Build the deal like distance was never the issue — because it isn't
The honest version of this post is short: an out-of-state sponsor is not a tax problem waiting to happen. It's a normal sponsorship with one extra line item to negotiate — travel, if they ever ask you to show up in person — and the same 1099 paperwork you'd owe anyone else past $2,000. That's it. Most of what racers assume is "complicated" about a distant sponsor is really just the plain old sponsorship basics they haven't built a system for yet: the W-9, the invoice, the tracker, the contract terms that cover an appearance before it's asked for.
That system is the whole point of The Funded Season Kit — eleven modules built like a real course, not a folder of PDFs, including the sponsor tracker and the "Before You Sign" contracts chapter that covers exactly this kind of term. If you want the lighter version first, The First Sponsor System has the same contracts chapter and sponsor list built in — the templates we use to run our own out-of-state partnerships, Virginia and all.
None of this is legal or tax advice. Every sponsor relationship is different, and a real accountant or attorney should look at anything with actual money attached before you sign it.
Do you believe?
Sources: IRS — Instructions for Forms 1099-MISC and 1099-NEC, OnPay — 2026 1099 reporting threshold changes under the One Big Beautiful Bill Act, Avalara — One Big Beautiful Bill Act changes 1099 thresholds, Sales Tax Institute — What is Nexus?, Bowditch & Dewey — Understanding the "Jock Tax", fynk — Endorsement Agreement template. The sales-tax-nexus conclusion is drawn from general nexus doctrine (economic nexus attaches to a seller making sales into a state) — I could not find a source addressing a pure sponsorship/advertising payment head-on, and said so above. The travel-reimbursement norm reflects contract-drafting convention from template and practice-guide sources, not a binding industry standard. OG Racing and FCP Euro are real LFR partners; neither relationship has required any special multistate tax handling beyond normal W-9/1099 paperwork. Nothing in this post is legal or tax advice.